Showing posts with label Bankers. Show all posts

JPMorgan Cuts Off Donations to Republicans Who Objected to 2020 Election Results

 Western Journal

June 6, 2021


The nation’s largest lender, JPMorgan Chase & Co., is set to resume political donations after pausing 

them in the wake of the Capitol incursion — but will maintain a freeze on donations to lawmakers 

who objected to the certification of the 2020 election.

Of course, like much of the narrative surrounding the Jan. 6 riot, this move is reliant upon the notion 

that objecting to the election is the same as barging into the Capitol in the middle of official 

proceedings with a motley crew of disgruntled voters and a far-left activist or two.

According to an internal memo obtained by Reuters, JPMorgan’s PAC will not donate to a “handful” 

of the 147 Republican lawmakers who voted to overturn the results of the 2020 election in January.

The pause will last through the 2022 midterm elections.

I have no memory of JPMorgan or anyone else ending donations to the many vocal and prominent 

lawmakers who told us for years that the 2016 election was illegitimate, do you?

Read the entire article

3-minute video: Public banks and monetary reform generate ~$1 million near-instant benefits for every US household: 2nd American Revolution more important than 1776

Washington's Blog

March 27, 2016


This article provides detailed history and data to explain what all macroeconomics courses teach: what we use for money is created as debt.
What these courses don’t usually teach are the consequences of creating what we use for money as negative numbers increasing forever: unpayable and ever-increasing total debt.

The top three benefits each of monetary reform and public banking total ~$1,000,000 for the average American household, and would be received nearly instantly.
Monetary reform is the creation of debt-free money by government for the direct payment of public goods and services. Creating money as a positive number is an obvious move from our existing Robber Baron-era system of only creating debt owed to privately-owned banks (a negative number) as what we use for money. Our Orwellian “non-monetary supply” of adding negative numbers forever causes today’s tragic-comic increasing and unpayable total debt. You learned these mechanics of positive and negative numbers in middle school, and already have the education and life experience to conclude with Emperor’s New Clothes absolute certainty that accelerating total debt is the opposite of having money. As a National Board Certified and Advanced Placement Macroeconomics teacher, I affirm this is also exactly what is taught to all economics students.

The public benefits of reversing this creature of Robber Barons are game-changing and near-instant. We the People must demand these, as .01% oligarchs have no safe way to do so without admission of literal criminal fraud by claiming that debt is its opposite of money.
The top 3 game-changing benefits of monetary reform:
  1. We pay the national debt in proportion to removing private banks’ ability to create what we use for money as debt in order to prevent inflation. We retire national debt forever.
  2. We fully fund infrastructure that returns more economic output than investment cost for triple upgrades: the best infrastructure we can imagine, up to full-employment, and lower overall costs.
  3. We stop the ongoing Robber Barons who McKinsey’s Chief Economist documents having ~$30 TRILLION in tax havens, and the Fed finding the US top seven banks creating shell companies to hide $10 trillion. This amount is about 30 times needed to end all global poverty, which has killed more people since 1995 than all wars and violence in all human history.

Public banking creates at-cost and in-house credit to pay for public goods and services without the expense and for-profit interest of selling debt-securities. North Dakota has a public bank for at-cost credit that results in it being the only state with annual increasing surpluses rather than deficits.

ESSENTIAL HISTORY: ‘FOREVER DEBT’ FEDERAL RESERVE SYSTEM INVENTED TO PAY INTEREST WITHOUT EVER EVER EVER REPAYING DEBT – DEFINITION OF ‘PONZI SCHEME’

Washington's Blog
February 27, 2016

The US federal government debt is now $19 trillion, having risen over a trillion each year of the Obama administration


Ponzi scheme: criminal fraud of paying existing “investors” only and always from new “investors.” Collapse occurs without new “investors” and/or existing “investors” panic to cash-in.
The US Federal Reserve is based on the 1694-created Bank of Englandbecause this model allows government finance with debt that is never meant to be repaid. It is an “investment” model that pays interest guaranteed through tax collection. Its invention was to finance England’s government and military in a history of continuous centuries of war.
It’s cleverness allowed British finance to fund a short-term empire over rival European powers.
Although we can appreciate this historical manipulation, this is a Ponzi scheme because the system collapses without new “investors” of government debt securities.
This Ponzi scheme model is our US Federal Reserve System today:
US Treasury securities of bills, notes, and bonds continuously mature and must be repaid if the owner chooses to cash-in rather than renew the debt security. The US federal government debt is now $19 trillion, having risen over a trillion each year of the Obama administration.
This amount of total debt compared with ~100 million US households means that the average US household of ~$50,000 annual income owes ~$190,000 each should investors withdraw from this US government funding scheme. If your household income is more than $50,000, then use this ratio to estimate your share for repayment; for example, a $150,000 annual family income would owe $570,000 if US Treasury holders requested repayment rather than continue rolling-over their loans to the US government.
Obviously, this system is at risk to at least devalue family’s existing savings to the degree the public reverses considering this Ponzi scheme as a “wise investment strategy.”
The great news is that the top three benefits each of monetary reform andpublic banking total ~$1,000,000 for the average American household, and would be received nearly-instantly.
Please read the above sentence a second time, then verify the following factual claims to confirm its objective accuracy.
Monetary reform is the creation of debt-free money by government for the direct payment of public goods and services. Creating money as a positive number is an obvious move from our existing Robber Baron-era system of only creating debt owed to privately-owned banks (a negative number) as what we use for money. Our Orwellian “non-monetary supply” of adding negative numbers forever causes today’s tragic-comic increasing and unpayable total debt. You learned these mechanics of positive and negative numbers in middle school, and already have the education and life experience to conclude with Emperor’s New Clothes absolute certainty that accelerating total debt is the opposite of having money. As a National Board Certified and Advanced Placement Macroeconomics teacher, I affirm this is also exactly what is taught to all economics students.
The public benefits of reversing this creature of Robber Barons are game-changing and nearly-instant. We the People must demand these, as .01% oligarchs have no safe way to do so without admission of literal criminal fraud by claiming that debt is its opposite of money.
The top 3 game-changing benefits of monetary reform:
  1. We pay the national debt in proportion to removing private banks’ ability to create what we use for money as debt in order to prevent inflation. We retire national debt forever.
  2. We fully fund infrastructure that returns more economic output than investment cost for triple upgrades: the best infrastructure we can imagine, up to full-employment, and lower overall costs.
  3. We stop the ongoing Robber Barons who McKinsey’s Chief Economist documents having ~$30 TRILLION in tax havens, and the Fed finding the US top seven banks creating shell companies to hide $10 trillion. This amount is about 30 times needed to end all global poverty, which has killed more people since 1995 than all wars and violence in all human history.
Public banking creates at-cost and in-house credit to pay for public goods and services without the expense and for-profit interest of selling debt-securities. North Dakota has a public bank for at-cost credit that results in it being the only state with annual increasing surpluses rather than deficits.
Top 3 game-changing benefits of public banking:
  1. a state-owned bank could abundantly fund all state programs and eliminate all taxes with just a 5% mortgage and credit card.
  2. a state-owned bank could create in-house and at-cost credit to fund infrastructure. This cuts nominal costs in half because, as you know, selling debt securities typically doubles the cost. For example, where I live we’re still dismantling the old Bay Bridge in NoCal from the upgrade that cost $6 billion, but the debt-service costs will add another $6 billion when it’s all paid.
  3. CAFRs (Comprehensive Annual Financial Reports) stash “rainy day” funds no longer required with a credit line from a public bank. In addition, the so-called “retirement funds” currently deliver net returns of just a few percent on good years, and negative returns on bad years (here, here). California’s ~14,000 various government entities’ CAFRs have a sampled-data total estimate of $8 trillion in surplus taxpayer assets ($650,000 non-disclosed assets per household, among California’s ~12.5 million households).
  4. Read the entire article

Keiser Report: Moths to Economic Flames

Keiser Report
January 31, 2016


In this episode of the Keiser Report, Max Keiser and Stacy Herbert discuss moths to the flame as corporations, individuals and whole nations self-liquidate on the pyre of bad debts. They look at the incredibly shrinking benefits of massive Japanese money printing and also at the proposal that Western oil giants self-liquidate as the best means of deploying their capital in a newly free oil market where the marginal producer once again sets the price. In the second half, Max interviews economics writer and researcher, Chris Martenson of PeakProsperity.com, about his new book, Prosper: How to Prepare for the Future and Create a World Worth Inheriting. They define ‘prosperity’ and name the best ways to create it for yourself, despite any global trends working against it.


SPECIAL REPORT: TPP GIVES OBAMA POWER TO DESTROY AMERICA

Infowars News
May 24, 2015


In this exclusive emergency address, Alex breaks down the hidden reasons behind the sinister Trans Pacific Trade Partnership.
The TPP is global domination by a fascist cartel bent on enslaving the world. Now the Senate has given fast-track authority to Obama to implement this secret plan and set fire to our Constitution, rules of law and ultimately our liberty and way of life.
Kentucky Senator and presidential candidate Rand Paul was among a host of lawmakers who staunchly opposed the secrecy surrounding the Trans Pacific Partnership bill, saying he disagrees with the proposed legislation “being held under lock and key.”
“I’m hesitant to give blanket authority on stuff we haven’t seen,” Senator Paul said earlier this month.
Yesterday, Paul was one of only five republican senators that voted against the final “fast-track” bill, in a vote that passed 62-37.
“Fast-track would allow Obama to send the Trans-Pacific Partnership (TPP) deal to Congress for an up-or-down vote” sans the ability to negotiate amendments, notes The Hill.
The TPA must still pass a House vote, which is why it’s imperative to contact your representatives and let them know you’re against H.R. 1314, the Trade Promotion Authority (TPA) or fast-track bill, which essentially grants the office of the president the power to do treaty by Executive Order.

Bank of America: Markets Are in a 'Twilight Zone' and It's Time to Hold More Cash and Gold

Bloomberg
May 19, 2015

In a note sent out this morning, Bank of America Merrill Lynch has a warning for investors: 
Investors remain trapped in “The Twilight Zone”, the transition period between the end of QE and the first rate hike by the Fed, the start of policy normalization...until (a) the US economy is unambiguously robust enough to allow the Fed to hike and (b) the Fed’s exit from zero rates is seen not to cause either a market or macro shock (as it infamously did in 1936-7), the investment backdrop will likely continue to be cursed by mediocre returns, volatile trading rotation, correlation breakdowns and flash crashes. For this reason we continue to advocate higher than normal levels of cash, adding gold and owning volatility in mid 2015. Given extremities of liquidity, profits, technological disruption, regulation, income inequality…potential for a cleansing drop in asset prices cannot be dismissed. Most likely catalysts: Consumer, Rates, A-shares, Speculation, High Yield.
The note also highlights two interesting disconnects in the markets:
  1. Investors say they are optimistic, but there is a high level of cash on the sidelines
  2. U.S. stock prices are at record highs, but equity funds are seeing outflows
Regarding the first point, one of Bank of America's surveys showed investor sentiment as being “risk-on," which it says is normally associated with less cash on the sidelines.
To the second point, the note says U.S. equity funds have suffered $100 billion of outflows in 2015 while the S&P 500 is near all-time highs, which its data says isn't exactly typical. 
The analysts led by Michael Hartnett attribute this to clients favoring European and Japanese equities at the expense of the U.S and that buying from those not captured in flow data (sovereign wealth funds, pension funds and central banks) could be what's giving U.S. equity indices a boost. 
The note hints that that you actually ought to sell in May and go away, at least for certain asset classes. 

The summer months offer a lose-lose proposition for risk assets: either the macro improves and the Fed gets to hike, which will at least temporarily cause volatility; or more ominously for consensus positioning, the macro does not recover, in which case EPS downgrades drag risk-assets lower. 

Even Central Bankers Now Admit QE Doesn’t Work

Washington's Blog
January 21, 2015


Even As European Central Bank Is Set to Unleash a Massive Round of Quantitative Easing, Central Bank Heads Admit QE Doesn’t Work

The former head of the Bank of England – Mervyn King – said today that more QE will not help the economy:
We have had the biggest monetary stimulus that the world must have ever seen, and we still have not solved the problem of weak demand. The idea that monetary stimulus after six years … is the answer doesn’t seem (right) to me.
Also today, William White – the brilliant economist who called the 2008 crisis well ahead of time, who is head of the OECD’s Review Committee and former chief economist for BIS (the central banks’ central bank)  slammed QE:
QE is not going to help at all. Europe has far greater reliance than the US on small and medium-sized companies (SMEs) and they get their money from banks, not from the bond market.
***
Even after the stress tests the banks are still in ‘hunkering down mode’. They are not lending to small firms for a variety of reasons. The interest rate differential is still going up.
***
Mr White said QE is a disguised form of competitive devaluation. “The Japanese are now doing it as well but nobody can complain because the US started it,” he said.
“There is a significant risk that this is going to end badly because the Bank of Japan is funding 40pc of all government spending. This could end in high inflation, perhaps even hyperinflation.
“The emerging markets got on the bandwagon by resisting upward pressure on their currencies and building up enormous foreign exchange reserves. The wrinkle this time is that corporations in these countries – especially in Asia and Latin America – have borrowed $6 trillion in US dollars, often through offshore centres. That is going to create a huge currency mismatch problem as US rates rise and the dollar goes back up.”
***
He deplores the rush to QE as an “unthinking fashion”. Those who argue that the US and the UK are growing faster than Europe because they carried out QE early are confusing “correlation with causality”. The Anglo-Saxon pioneers have yet to pay the price. “It ain’t over until the fat lady sings. There are serious side-effects building up and we don’t know what will happen when they try to reverse what they have done.”
The painful irony is that central banks may have brought about exactly what they most feared by trying to keep growth buoyant at all costs, he argues, and not allowing productivity gains to drive down prices gently as occurred in episodes of the 19th century. “They have created so much debt that they may have turned a good deflation into a bad deflation after all.”
The former long-term head of the Federal Reserve (Alan Greenspan) says that QE has failed to help the economy.
Numerous academic studies confirm this. And see this.
Indeed, many high-level economists – including Federal Reserve economists and the main architect of Japan’s QE program – now say that QE may cause deflation and harms the economy in the long run.
Economists also note that QE helps the rich … but hurts the little guy. QE is one of the main causes ofinequality (and see this and this). And economists now admit that runaway inequality cripples the economy. So QE indirectly hurts the economy by fueling runaway inequality.
A high-level Federal Reserve official says QE is “the greatest backdoor Wall Street bailout of all time”. And the “Godfather” of Japan’s monetary policy admits that it “is a Ponzi game”.

Martin Armstrong Warns Civil Unrest Is Rising Everywhere: "This Won't End Pretty"

Zero Hedge
June 28, 2014

The greatest problem we have is misinformation. People simply do not comprehend why and how the economic policies of the post-war era are imploding. This whole agenda of socialism has sold a Utopian idea that the State is there for the people yet it is run by lawyers following their own self-interest. The pensions created for those in government drive the cost of government up exponentially with time. The political forces blame the rich and this merely creates a class warfare with no resolution for the future. Even confiscating all the wealth of the so-called rich will not sustain the system. Consequently, we just have to crash and burn and start all over again.
The Guardian reported that some 50,000 people marched in London to protest against austerity. They cried: “Who is really responsible for the mess this country is in? Is it the Polish fruit pickers or the Nigerian nurses? Or is it the bankers who plunged it into economic disaster – or the tax avoiders? It is selective anger.”
The exploitation by the bankers has been really a disaster. They have been their own worst enemy and in the end, they have become the symbol that inspires class warfare if not revolution. They are not the representatives of those who produce jobs. They are merely those who wanted to trade with other people’s money for free. When they win, it is their’s, but any losses are passed to the taxpayers. Bankers should be bankers – not hedge fund managers who keep 100% of the profits using other people’s savings.
Glass-Steagall Signing-Repeal
The repeal of Glass Steagall was the final straw that broke the back of the world economy. That was the single worst act that could have ever been done and we are now paying the price in spades. The collapse from 2007 has wiped out even the liquidity of the markets. The second worst act was the creation of the euro when the real goal was the federalization of Europe from the outset. That undermined the entire European banking system and has led to a serious undermining of the entire global economy.
The solutions from politics will always be the same – grab more power. We are in a downward spiral of liberty and how far we go down this path to the future will be determined by the people and if they at least wise up and see this is not class warfare, it is the people against government. This is why I say career politicians are dangerous for they can be bought way too easily as Clinton was to open the flood gates for the bankers.
This is not going to end pretty. The question is when does society wake up? Just how high will this price be that we have to pay? They will blame the rich and the idiots will cheer – get them. What will happen when there is no more wealth to hunt? We end up with a communist state by default – no wealth, just career politicians who blame everyone but themselves.

Former Banker Exposes Globalist Plan for U.S. Economic Collapse

SIC SEMPER TYRANNIS!!!
Mark Matheny
May 8, 2014

Mark Matheny continues the discussion of the Collapse of the U.S. economy. In this episode:
Former Banker and Congressional Investigator, Norman Dodd explains his experience in uncovering the true controllers of American policy and their planning of the economic collapse we are about to experience.
"We will never have sound banking in the United States again...." this was a statement told to Norman Dodd by his superiors a very prominent Banking Institution...

SI
Discover Politics Internet Radio with Mark Matheny on BlogTalkRadio

Sterling to go plastic, Bank of England decides....the end of Paper notes

The Guardian 
December 17, 2013

Matheny's Note: this is getting a step closer to the goal of a paperless currency. We are sure to possibly see other nations doing the same thing if this is successful. They will implant micro censors in these bills no doubt to track them and verify their authenticity, if they haven't already done so.


Polymer banknote
A sample polymer ten pound banknote. Photograph: Chris Ratcliffe/Press Association
The Bank of England will announce plans on Wednesday to press ahead with switching to plastic banknotes, starting with the new Sir Winston Churchill £5 note in 2016.
The decision on polymer notes will mark the beginning of the end for 320 years of paper notes from the Bank. The move by Threadneedle Street follows Bank governor Mark Carney's native Canada, where plastic notes are being rolled out, and Australia, where they have been in circulation for more than two decades.
Carney launched a public consultation on polymer banknotes, seen as cleaner and more durable, shortly after arriving at the Bank this summer. However, the Bank's notes division has been considering plastic money for several years.

Quantitative Easing has become heroine to the financial markets: Federal Reserve balance sheet hits $4 trillion this week.

MyBudget360
December 16, 2013

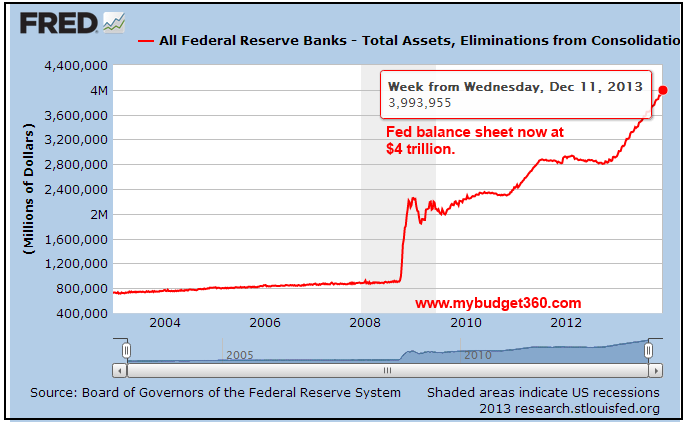
Addiction is never an easy battle to overcome.  This also applies to easy money addiction that is now part of the Quantitative Easing economy.  The Fed’s extraordinary measures are now appearing to be more permanent measures.  Every time the whispers of tapering are made the markets respond accordingly signifying that the stock market is fully addicted on easy money.  There is really no backing out of QE without some sort of pain.  Any addict pulling themselves away from a drug suffers some brief or long period of withdrawal.  Yet the long-term benefits are obvious.  In this case, the Fed is not only avoiding tapering but getting more aggressive in their QE heroine.  This week, the Fed’s balance sheet crossed the $4 trillion barrier.  Of course few people pay attention to the Fed’s balance sheet but the fact that the Fed has created a second housing mania fueled by investor money is startling.
QE forever
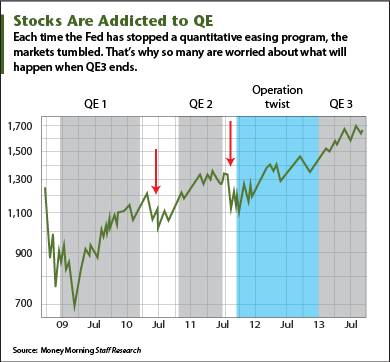
It is interesting that each time the hint of a taper was made the market responded by pulling back.  The markets are fully addicted to this low rate environment brought on by the Fed buying up long-term MBS on the cheap.  Who in the world would take on a 4 percent mortgage in this kind of market?  Apparently only the Fed.  So it is no surprise that the markets respond with pain each time the QE taper is announced:
When-QE-ends
Source:  Money Morning
It is fairly clear that pulling back on QE will have an impact on stocks. The entire financial edifice is now building off of the assumption that QE will last forever.  This has created deep distortions in wealth and has also created a secondary housing mania where big funds are rushing out to buy real assets with artificially low rates.
It is comical to hear that the Fed is tapering because looking at the Fed balance sheet we see absolutely no signs of any sort of tapering:
fed balance sheet
To the contrary, the Fed has become more aggressive in buying up MBS via their QE operations.  The Fed is now essentially the mortgage market.  In spite of this poor allocation of resources, wealth inequality in the US has only become more pronounced.  As we have highlighted before most Americans have very little invested in the stock market so the gains here are of little consequence to the vast majority.  Companies have used the economy to cut wages and also to slam employee benefits.  Behind the scenes however high level executives especially in the financial industry have used easy money handouts from the Fed to lever up once again in the real economy.
Don’t forget the debt
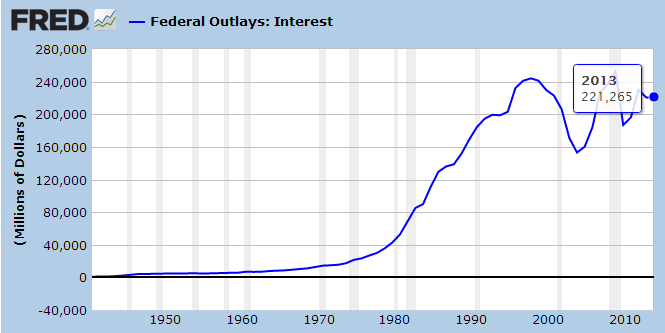
We are now paying a substantial sum in interest payments on our debt:
fed interest costs on debt
The only thing keeping things down is the low rate we are able to garner around the world.  The Fed is aware of this and realizes any sizeable moves in interest rates will cause a dramatic rise in interest payments on debt.  Better to inflate away our debt so long as we can find a market for this.  Yet that is the problem with QE since the Fed is essentially the only player.  There is virtually no market for 30 year mortgage rates at current price levels.  The market is fully addicted on QE.
Getting off QE heroine does not look like it will happen.  So why the constant discussions of tapering?  The Fed is a giant confidence game and many are starting to realize this.  Banks understand that any sort of unwind will impact the stock market so better to chase yields in real assets and crowd out regular households.  This is why inequality keeps getting worse in the US in spite of the stock market being near a record high.  The financial industry is fully addicted to this QE heroine and will say anything to keep their pusher providing this easy money.  $4 trillion will not be the only milestone that is crossed even though the taper is always being mentioned.

The Real Black Friday

Ebullient consumers mask the real peril of stock market madness
Kurt Nimmo
Infowars.com
November 29, 2013
Black Friday opened with a predictable boom that resounded favorably through the Big Casino on Wall Street. Stocks on the Dow Jones climbed to 22 points to 16,119 soon after opening this morning. Standard & Poor’s index bumped up a modest two points to 1,809 and the Nasdaq jumped 15 points to 4,060.
“Consumers weren’t the only ones shopping on Black Friday. Stocks pushed even higher into record territory, as investors returned from Thanksgiving break for a short, final day of trading in November,” CNN reports.
Despite modest gains on the stock market, the hype that revolves around Black Friday seems to be losing some of its media generated luster. The large retails chains – Wal-Mart, Target, Best Buy, Kohl’s, JCPenney, Kmart and Toys R Us – have downgraded expectations.
“Indeed the latest poll from AC Nielsen’s Holiday Spending Forecast study, which surveys over 22,000 households throughout the US, indicates that 85% of consumers plan on skipping the stores on Black Friday this year,” Zerohedge reports. “This is up from 82% in 2012, 82% in 2011 and 80% in 2010 so a negative four-year trend is taking shape. Black Friday shopping seems to be merging with Cyber Monday as well with 51% of consumers say they will do their Black Friday shopping online this year. According to the National Retail Federation, the holiday season generally accounts for about 20% of the retail industry’s annual sales so all eyes will be on retail sales updates/snippets over the weekend.”
The bullish frame of mind ruling the stock market is little more than voodoo. “We think odds favor some sort of a pullback in the coming weeks and months,”Jonathan Krinsky, chief market technician at MKM Partners, told the Wall Street Journal. For more than a decade, stocks have rallied in late summer only to fall off between Thanksgiving and Christmas. The bump gets harder which each passing year and nobody knows when it will finally bottom out.
The Real Black Friday
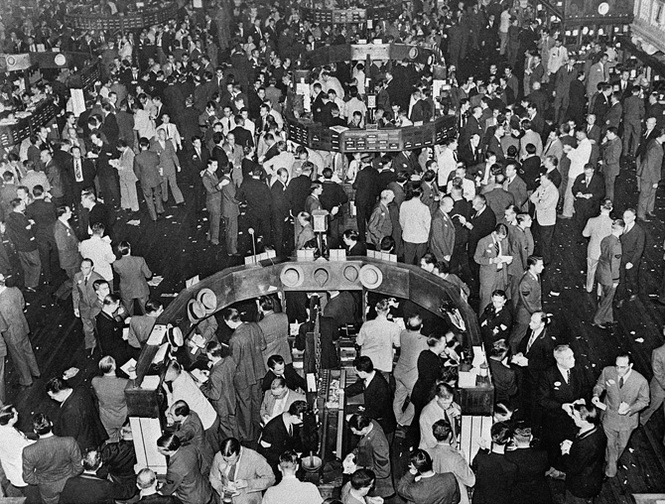
The real Black Friday, October 29, 1929.
The real Black Friday happened on a Tuesday, October 29, 1929
The real Black Friday happened on a Tuesday, October 29, 1929, when the stock market experienced its largest one day drop in history – a precipitous 22% – and heralded in the first Great Depression.
This calamitous event was created by the Federal Reserve. It had inflated the money supply by 61.8 percentbetween 1921 and 1929 and created a massive inflationary bubble that imploded on that black day in October.
There was also a Black Friday on September 24, 1869, when two gold speculators, Jay Gould and James Fisk, cornered the market on the New York Gold Exchange. The scandal resulted in the Grant administration being called the Era of Good Stealings. It was an early demonstration of how the stock market can be manipulated.
Academics and establishment media talking heads like to say the Great Depression was caused by the excesses of free market capitalism. In fact, it was created by the Federal Reserve and its conniving cartel of banksters.
Debunking the popular myth, Julie Borowski cites the economist Henry Hazlitt who wrote that “worse than the slump itself may be the public delusion that the slump has been caused, not by the previous inflation, but by the inherent defects of ‘capitalism.’” The slump was, in fact, created by the Fed with its notorious whipsaw economic policies of artificial boom and bust.
Another economic catastrophe is now in the works and it looks like it may be set into motion by China. It has called for a “de-Americanized” world where the dollar is no longer the global reserve unit. China is now the largest single holder of U.S. government debt with 26 percent of all foreign-held U.S. Treasury securities, which represents 8% of total U.S. government-generated debt.
“Foreign investors in U.S. dollar assets have seen big losses measured in dollars, and still bigger ones measured in their own currency. While unlikely, indeed highly improbable for public sector investors, a sudden rush for the exits cannot be ruled out completely,” warned the bankster elite from their tower in Basel, Switzerland, after the plug was pulled on the economy back in 2008.
When China and other debt holders finally back away from the dollar, “the consequences for the U.S. economy will be absolutely catastrophic and every single American will feel the pain,” writesMichael Snyder. “The standard of living that all of us are enjoying today depends largely upon China. They can bring down the hammer at any moment and they know it.”
For now, crowds of ebullient consumers are reveling at Walmart, a store packed to the rafters with cheap flat screen televisions and other electronics manufactured by China’s labor gulag slaves. The good times continue to limp along on the sputtering tail wind of the greatest economic expansion in history. That wind will soon stop blowing. When it does we will all experience the greatest single bust in the history of the world.